
Operator Landscape and Competitive Dynamics
How a dozen operators are shaping a $7B market — and who has the structural advantage.
Operators in market
Tier 1, Tier 2, Tier 3 conglomerate entrants
Operational IT load
end-2025; Top-5 control ~70%
Hyperscaler commitments
AWS + Microsoft + Google, post-Oct 2024
IPO-bound operators
Yotta, Nxtra, CtrlS, Sify Infinit Spaces
Live operator-relevant context: day-ahead price ₹3,420/MWhlast known · live capex landscape at /data-centres · operator economics commentary in /insights.
India's DC Market Has Crystallized into Three Distinct Tiers
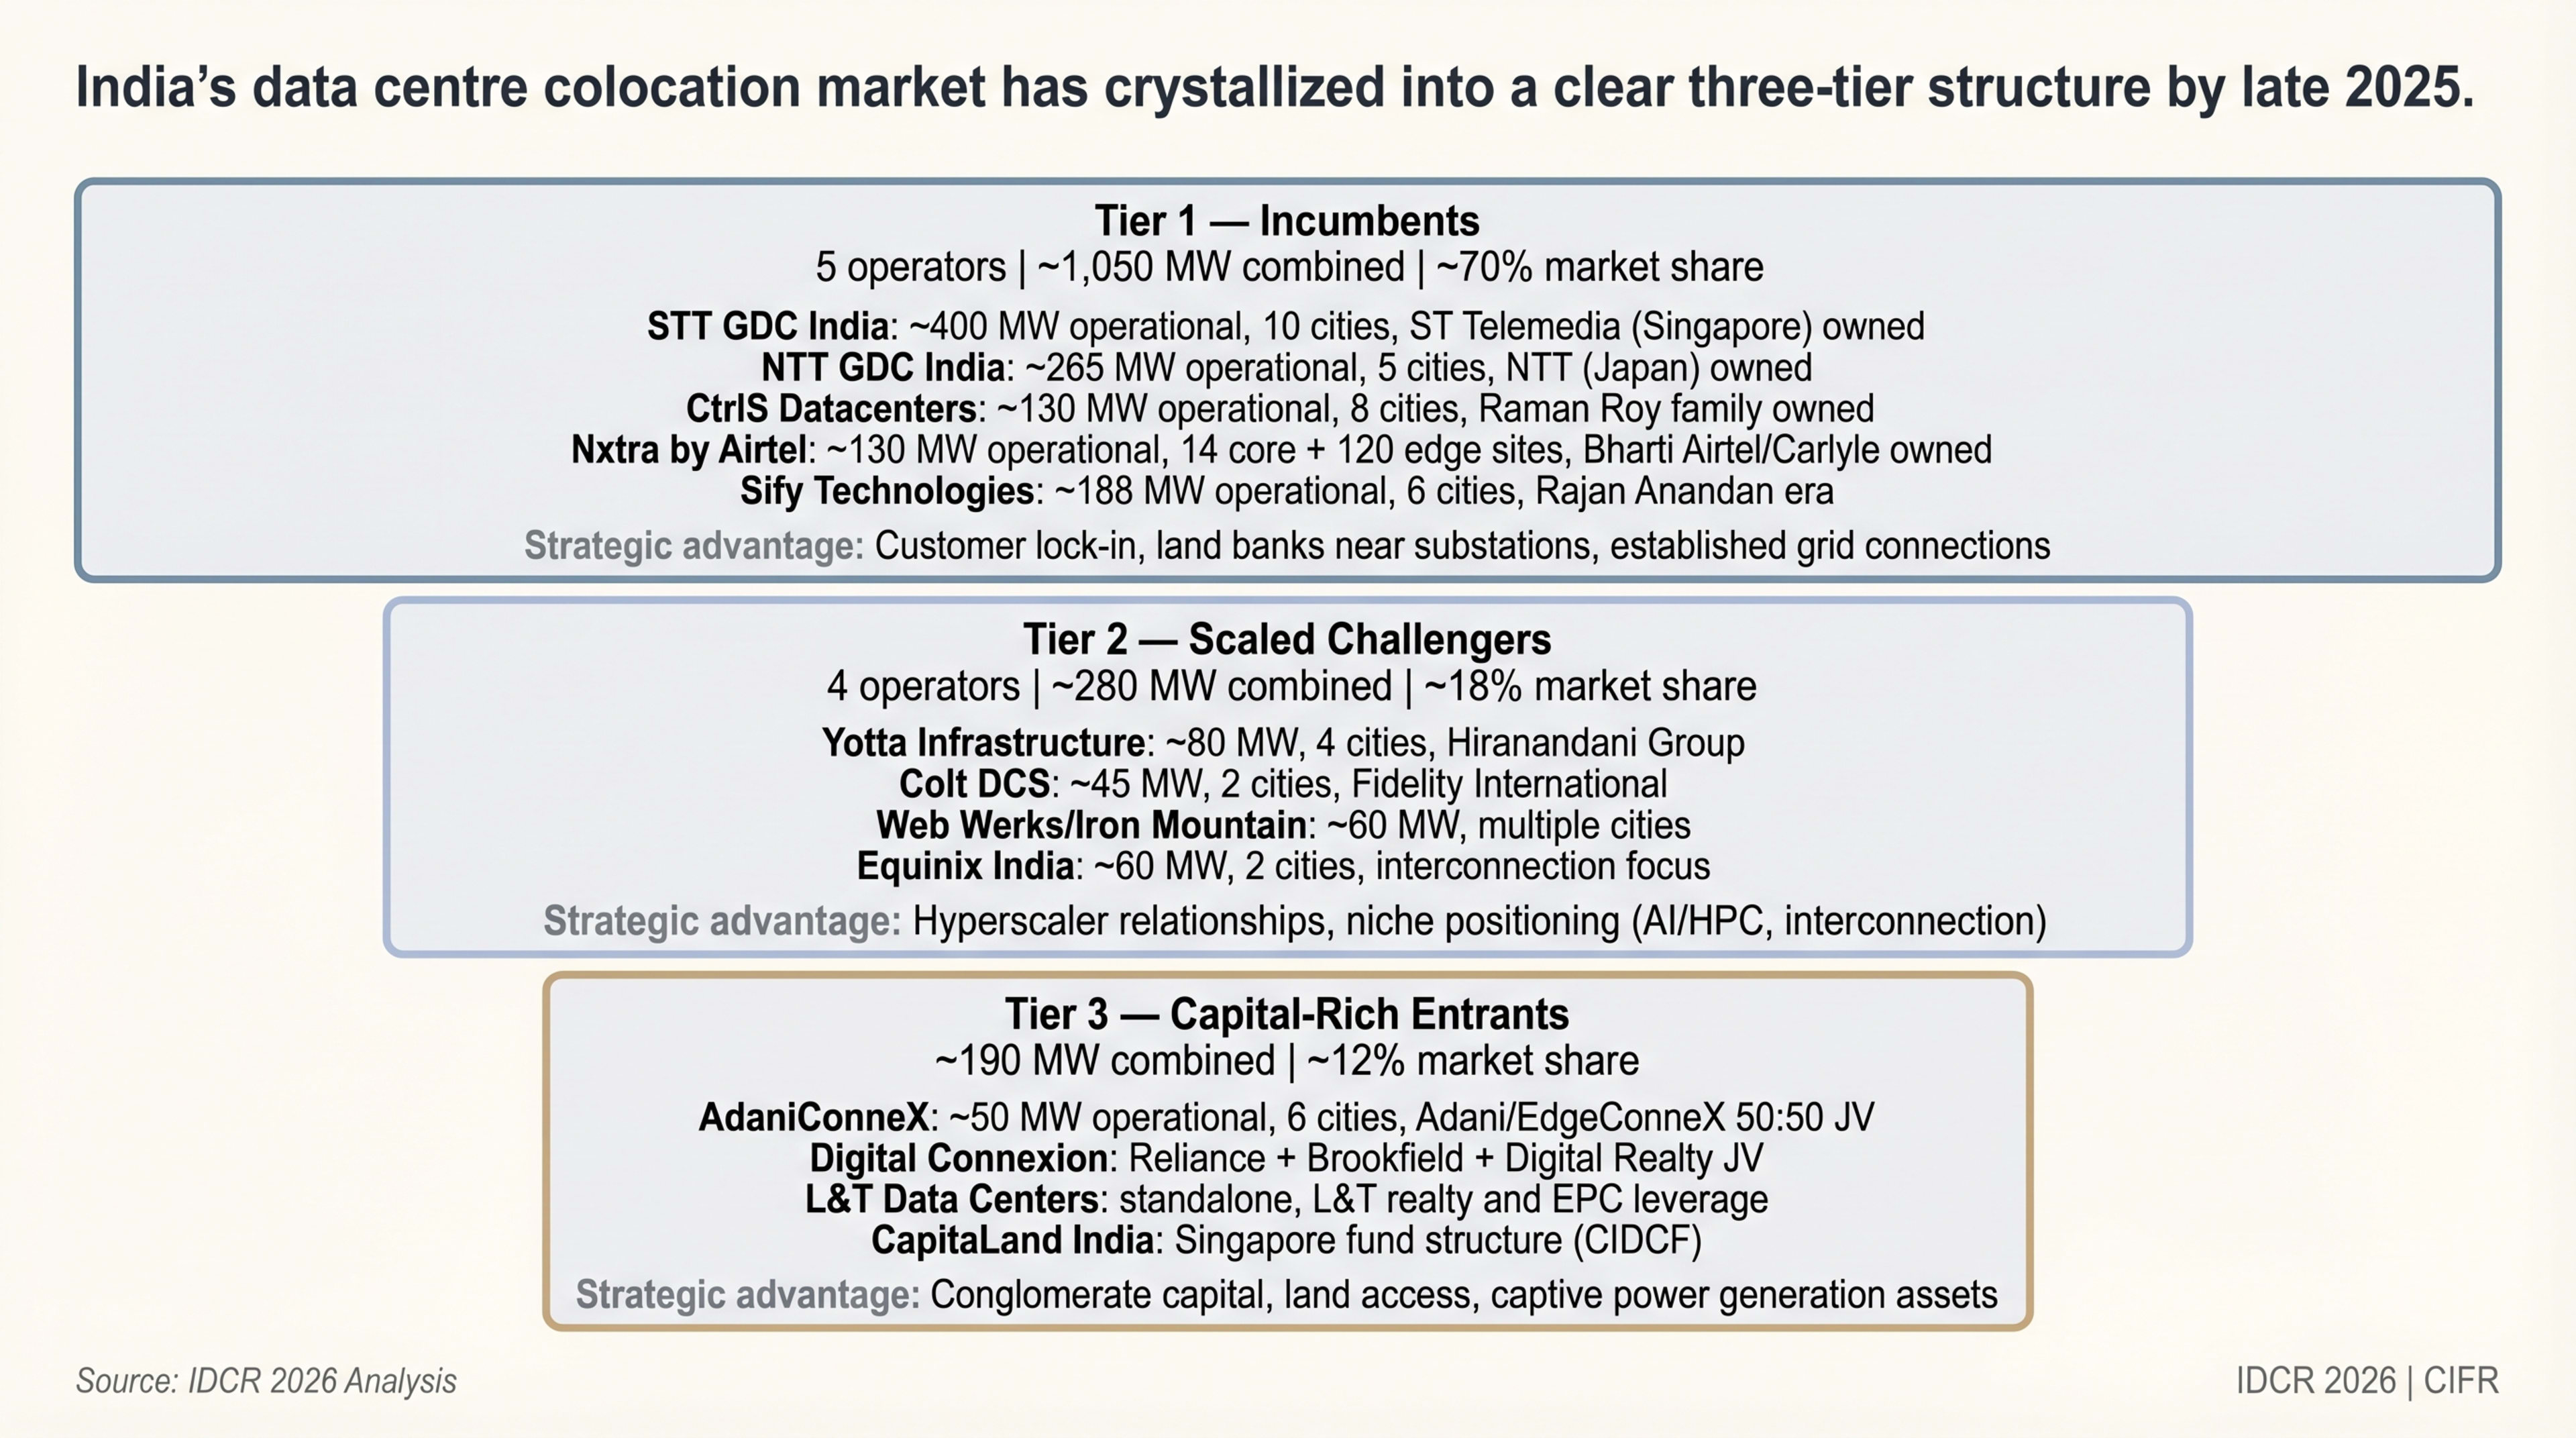
India's colocation market has crystallised into a three-tier structure by late 2025 (Houlihan Lokey· Houlihan LokeyDec 2025; Cushman & Wakefield· C&WH1 2025). Tier 1 incumbents control ~75% of operational capacity through five operators: STT GDC (400 MW, see Maharashtra/Karnataka), NTT (265 MW, primarily Mumbai), CtrlS (130 MW, Hyderabad-led), Nxtra (130 MW, pan-India), and Sify (188 MW, Noida-led). Tier 2 comprises scaled challengers with 30--80 MW each: Yotta, Colt DCS, Web Werks/Iron Mountain, and Equinix. Tier 3 entrants---AdaniConneX, Digital Connexion (Reliance--Brookfield--Digital Realty), and CapitaLand---bring conglomerate capital but limited operational deployment so far.
| Three-Tier Market Structure | ||||
|---|---|---|---|---|
| Tier | Operators | Combined Capacity | Market Share | Strategic Advantage |
| Tier 1 — Incumbents | STT GDC, NTT, CtrlS, Nxtra, Sify | 1,050 MW | 70% | Customer lock-in, land banks, grid connections |
| Tier 2 — Scaled Challengers | Yotta, Colt DCS, Web Werks/Iron Mountain, Equinix | 280 MW | 18% | Hyperscaler relationships, niche positioning |
| Tier 3 — Capital-Rich Entrants | AdaniConneX, Digital Connexion, CapitaLand | 190 MW | 12% | Conglomerate capital, land access, energy assets |
Source: IDCR 2026 estimates based on Houlihan Lokey Dec 2025; company disclosures; CBRE H2 2025
STT GDC Leads on Installed Base, but NTT and Nxtra Are Closing the Gap
| India DC Operator Leaderboard — Operational Capacity (Q4 2025) | ||||||||
|---|---|---|---|---|---|---|---|---|
| Rank | Operator | Ownership | Operational MW | Pipeline MW | Cities | Key Clients | Revenue (est.) | Expansion Highlight |
| 1 | STT GDC India | ST Telemedia (Singapore) | 400 | 550 | 10 | Hyperscalers, BFSI | $450M (28% share) | $3.2B for 550 MW over 5–6 yrs |
| 2 | NTT GDC India | NTT (Japan) | 265 | 550+ | 5 | Cloud, BFSI, Govt | $320M ( 20% share) | 400 MW Hyderabad AI campus; $1.2B committed |
| 3 | CtrlS Datacenters | Raman Roy family | 130 | 600+ | 8 | BFSI, Pharma, IT | ₹1,567 Cr ( $185M) | 612 MW Hyderabad mega-campus |
| 4 | Nxtra by Airtel | Bharti Airtel / Carlyle | 130 | 400+ | 14 core + 120 edge | Airtel captive, Cloud | $150M (15% share) | $1B fundraise; 1 GW target in 3–4 yrs |
| 5 | Sify Technologies | Rajan Anandan era | 188 | 350+ | 6 | IT Services, Cloud | $140M (est.) | Noida 02 hyperscale; INR 3,000 Cr investment |
| 6 | Yotta Infrastructure | Hiranandani Group | 80 | 500+ | 4 | AI/HPC, Govt, Cloud | $100M (est.) | $2B Nvidia AI hub partnership; FY27 IPO planned |
| 7 | Equinix India | Equinix (US) | 60 | 100+ | 2 | Interconnection, Fintech | Not disclosed | Chennai IBX launched Sep 2025 |
| 8 | AdaniConneX | Adani/EdgeConneX 50:50 | 50 | 2,000+ | 6 | Hyperscalers (Google) | Early-stage | $15B Google Vizag partnership; 5 GW target |
| 9 | Colt DCS | Fidelity International | 45 | 100+ | 2 | Enterprise, Fintech | Not disclosed | Mumbai, Navi Mumbai expansion |
Source: Company disclosures; Houlihan Lokey Dec 2025; ICRA Sep 2025; Blackridge Research Feb 2026. Revenue estimates are IDCR 2026 approximations based on publicly available data and may differ from audited figures.
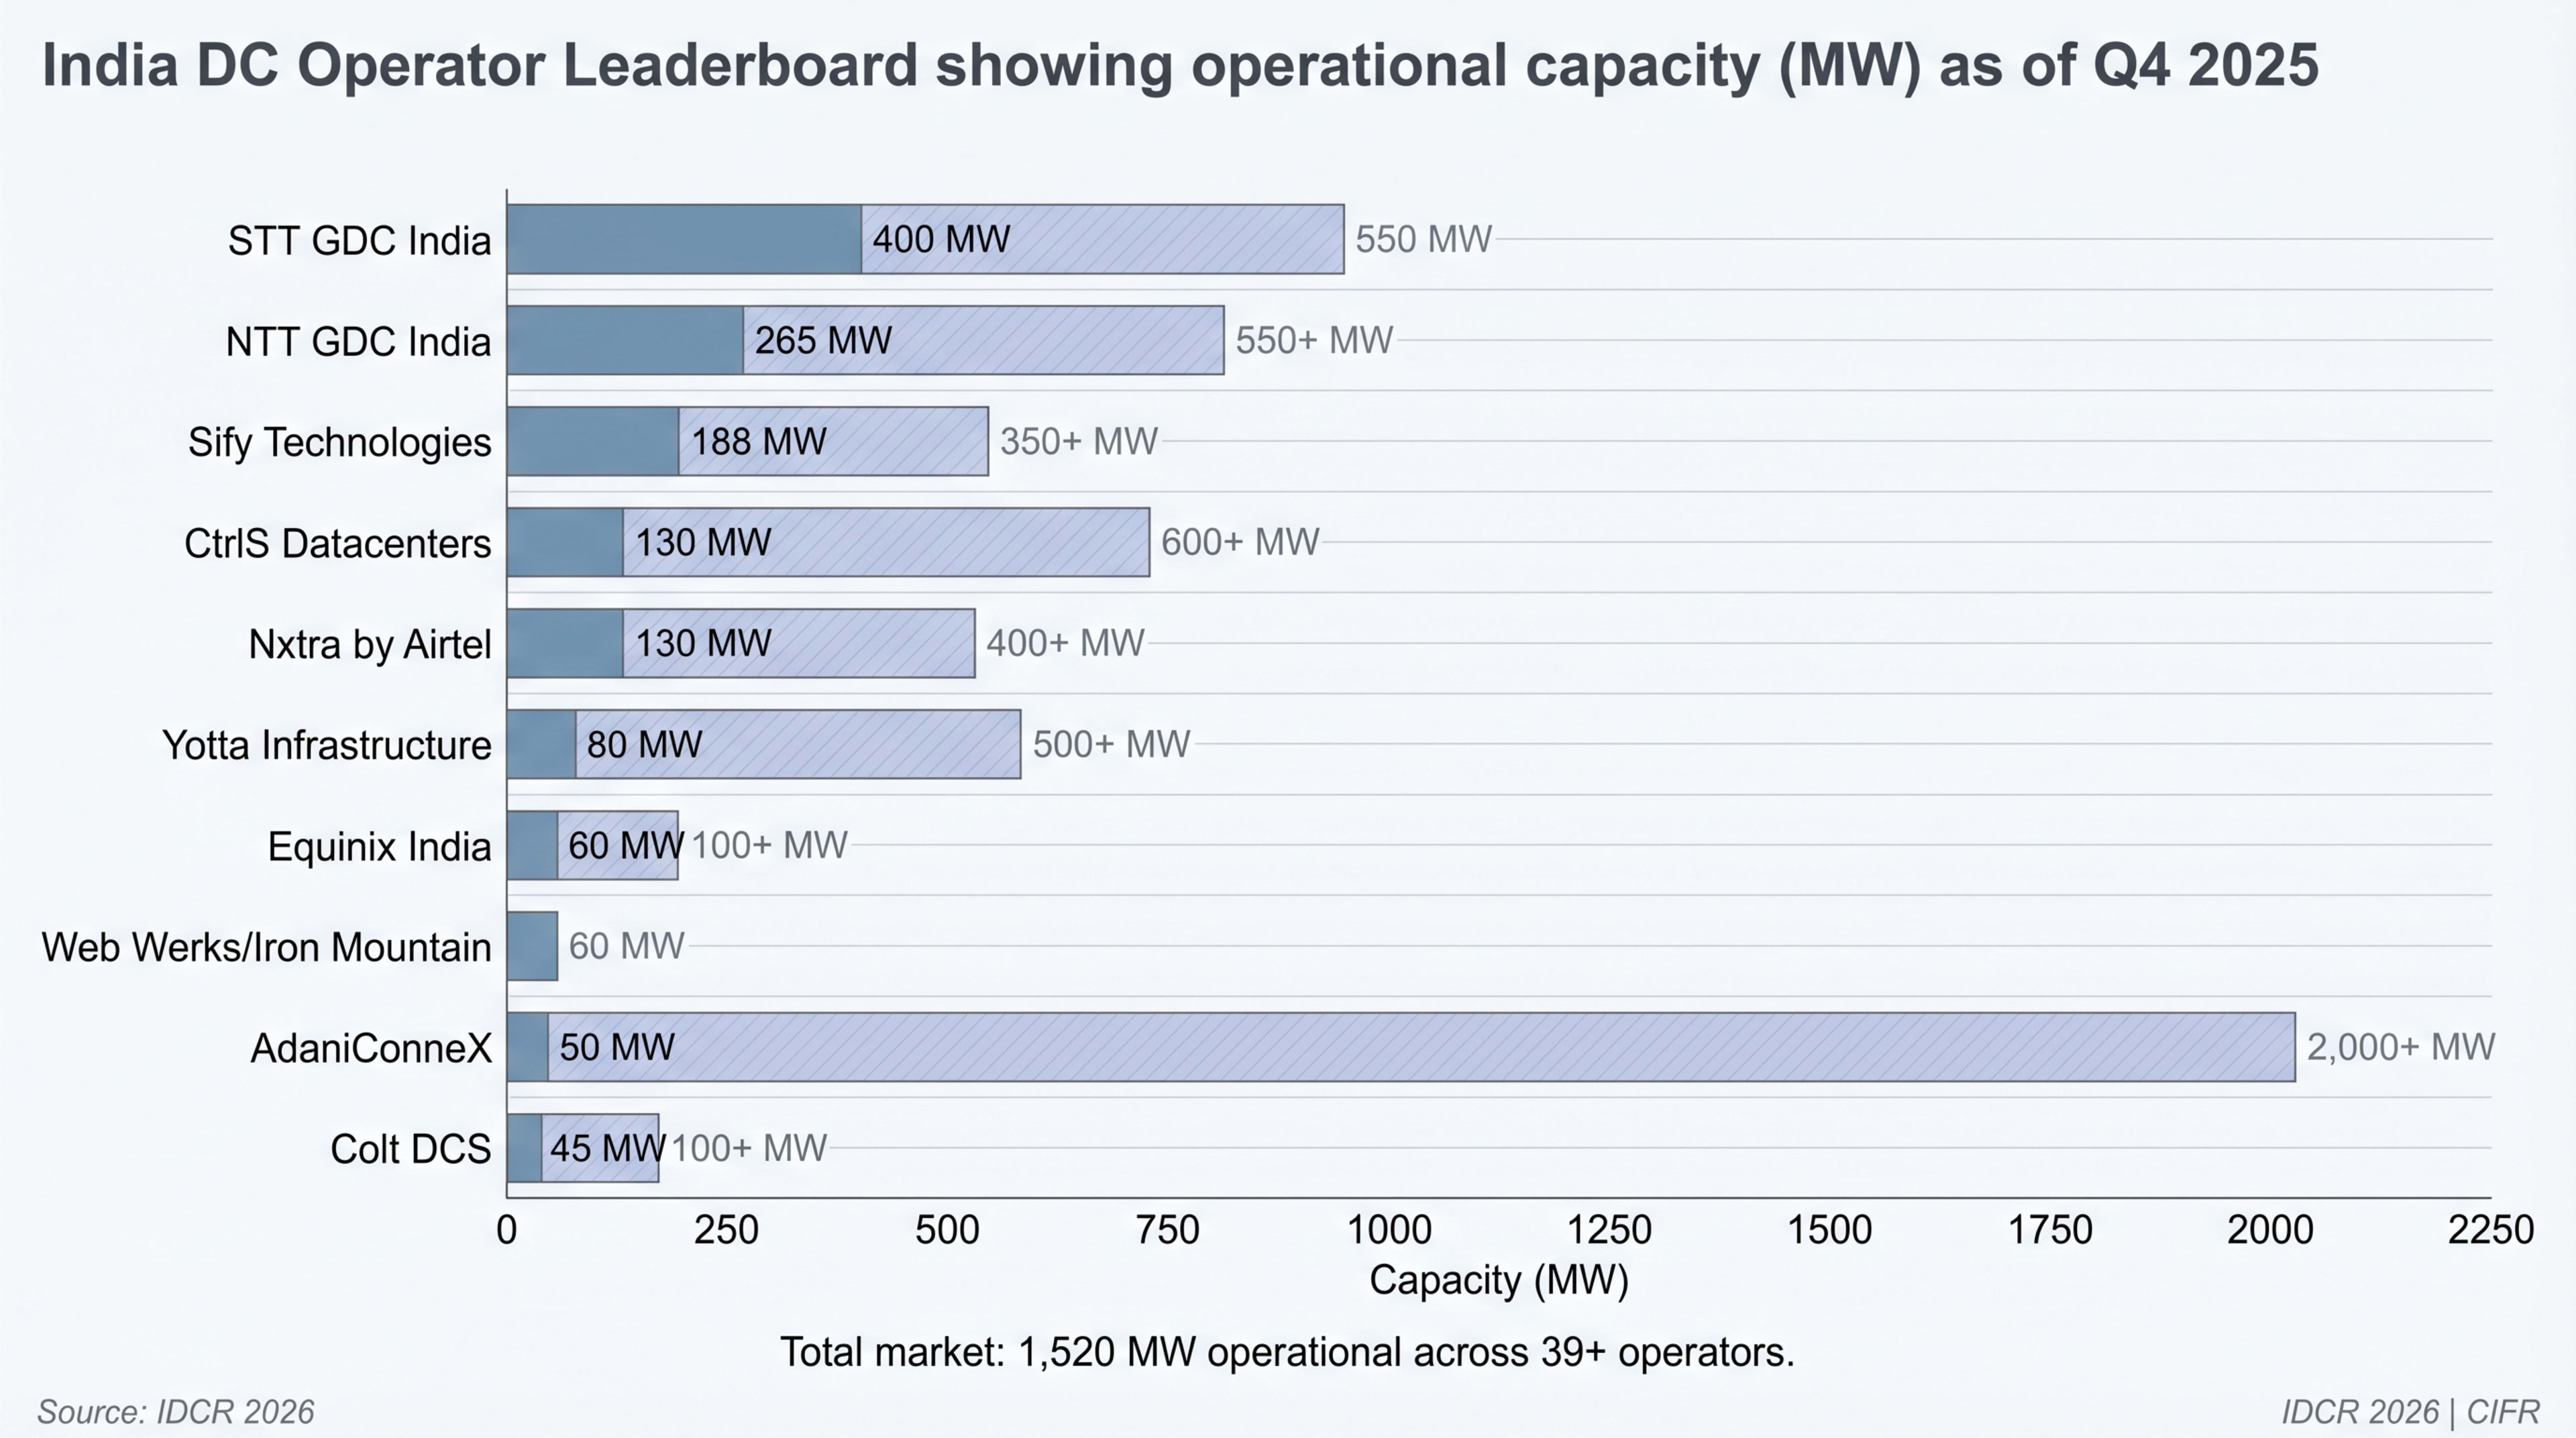
Note: Operational capacity figures in this table represent IT load capacity as reported by Cushman & Wakefield H1 2025 and operator disclosures. Company-reported figures may include capacity under commissioning or use total facility power definitions that yield higher numbers. Where discrepancies exist with company claims, we note the difference.
Hyperscalers Commit $45.2B to DC Infrastructure — Bifurcating Demand
Hyperscalers shifted decisively towards captive and JV builds in 2025, anchored by four major commitments:
- AWS: $12.7B (by 2030) for 500+ MW, primarily Mumbai-focused, via partnerships with NTT and STT GDC.
- Microsoft: $17.5B (2025–2029) for 300+ MW cloud and AI infrastructure, including a new Hyderabad region (mid-2026).
- Google: $15B for a 1 GW Visakhapatnam AI Hub with AdaniConneX (see Chapter 4, Deal #12).
- Meta/Reliance: $12–15B for 1 GW AI capacity as a joint venture.
Colocation remains essential for interconnection-heavy workloads, network peering, and regional edge presence. IDCR estimates 40--50% of hyperscaler pipeline capacity will flow through colocation partnerships; the remainder pursues pure captive builds.
| Hyperscaler India Commitments (as of March 2026) | ||||
|---|---|---|---|---|
| Hyperscaler | Total Commitment | Primary Model | Key Partners | **Target Capacity |
| AWS | $12.7B by 2030 | Captive + Colo | NTT, STT GDC | 500+ MW |
| Microsoft | $17.5B | Captive + Colo | STT, CtrlS, Sify | 300+ MW |
| $15B (Vizag) | JV (AdaniConneX) | AdaniConneX | 1 GW | |
| Meta/Reliance | $12–15B | JV | Reliance Jio | 1 GW |
| Digital Connexion | $11B | JV (Reliance-Brookfield-Digital Realty) | Equal thirds | 1 GW (Vizag) |
Keep reading — free, takes 30 seconds
Operator Landscape and Competitive Dynamics continues with 1,450 words and 17 figures.